
The Hidden Anxiety Behind Buying Your First Home
Let's talk about the cold sweat you get when a real estate agent asks for your pre-approval letter. You thought you just had to find a house you liked, maybe save up some cash, and the bank would gladly hand over the rest. Instead, you are hit with a wall of confusing math, credit score panic, and the sudden realization that you have no idea how mortgages actually work. Do not worry—you are not alone, and beating the bank at their own game is a lot easier once you know their hidden rules.
I still clearly remember staring at my laptop screen at 2 AM, feeling completely overwhelmed by real estate jargon. I had just found what looked like my absolute dream home on a popular property listing website. The photos showed a beautiful kitchen, a large backyard for my dog, and a cozy living room.
I was so excited that I immediately emailed the real estate agent to set up a tour the very next morning. When the agent replied, her first question completely stopped me in my tracks. She simply asked, "Do you have your mortgage pre-approval letter ready to go?"
I had no idea what that letter was, let alone how to get one. I thought you just found a house you liked, told the bank you wanted to buy it, and they gave you the money. My lack of preparation meant I missed out on that beautiful home, and another buyer snatched it up a few days later.
That rejection hurt deeply, and it made me realize how unprepared I truly was for the home-buying journey.
You might lie awake at night wondering if your credit score is high enough. You worry if your student loans will automatically disqualify you from getting a mortgage. This constant fear of financial rejection creates a huge amount of unnecessary stress in your daily life.
When you do not understand the rules of the game, every single step feels like a hidden trap waiting to spring. But the good news is that securing a home loan does not have to be a miserable experience. You just need a clear, easy-to-follow map that shows you exactly what lenders are looking for.
By removing the mystery from the application phase, you can finally take back your confidence and peace of mind. Let us break down exactly how you can prepare yourself to get approved without losing your sanity.
The "No-Panic" Mortgage Checklist
- Freeze your credit: Do not apply for new loans, buy furniture on credit, or close old accounts right before applying for your home.
- Audit your DTI: Keep your total monthly debt payments (including the estimated new house payment) well under 43% of your gross income.
- Track every single dollar: Have a clear paper trail for large cash deposits so underwriters do not suspect you are hiding secret loans.
- Shop around: Never settle for the first bank you talk to; always compare "Loan Estimates" to find the absolute lowest fees.
Building Your Bulletproof Financial Profile
Before you even think about talking to a bank or a lender, you need to look at yourself in the mirror financially. Getting a home loan is basically a massive trust exercise between you and a financial institution. They are about to hand you hundreds of thousands of dollars, and they need hard proof that you will pay it back.
Think of this phase like taking your car in for a complete mechanical inspection before a long road trip. You want to find any hidden leaks or broken parts before you are stranded on the highway. In the financial world, this means pulling your credit reports from all major reporting agencies.
Do not just look at the final three-digit number at the top of the page. You need to review every single line of that report to make sure there are no scary surprises.
Sometimes, a simple mistake like an unpaid medical bill from five years ago can drag your score down. If you spot an error, you have the legal right to dispute it and get it removed from your record. Fixing these small errors can give your score a nice bump before a lender even looks at it.
Myth vs Reality: The Credit Score Confusion
A lot of first-time buyers believe they need a perfect credit score to even think about applying for a loan. This is one of the most common myths that keeps perfectly qualified people renting for way too long.
Myth: You must have a flawless credit score of 800 or above to buy a home.
Reality: Many government-backed loan programs accept scores much lower than you might expect. Conventional loans often look for a good score, but they certainly do not demand absolute perfection from normal applicants.
The key is consistency in your payment history over the last few years. Lenders want to see that you pay your credit cards, auto loans, and current rent on time, every single month. If you have a few late payments from your college days, do not panic.
Just focus on keeping your current credit card balances low and paying every new bill the day it arrives. This consistent, responsible behavior shows the bank that you have matured and can handle a large mortgage payment.
Here is a Pro Tip for you: When I first applied, I aggressively paid off a very old credit card and closed the account, thinking it would make me look good. I later realized that closing an old account actually hurt my credit history length and dropped my score right before the application! Always keep your oldest accounts open and active, even if you just use them for a small monthly subscription.
The Paperwork Avalanche (And How to Survive It)
Once your credit profile is looking healthy, it is time to start digging through your file cabinets. Lenders will ask for a mountain of documents to verify that everything you tell them is the absolute truth.
If you wait until the last minute to find these papers, you will be tearing your house apart in a blind panic. I highly recommend creating a dedicated digital folder on your computer to store all these files safely.
The very first thing they will ask for is proof of your income. For most standard employees, this means providing your most recent pay stubs covering the last thirty days. You will also need to hand over your tax returns from the previous two years.
Why do they need so much history?
The bank wants to see that your income is stable, reliable, and unlikely to disappear tomorrow. If you recently changed jobs, they might ask for an offer letter or an email from your new human resources department.
If you are a freelancer or a self-employed worker, this step requires a little more heavy lifting. You will likely need to provide detailed profit and loss statements for your business. You might also need letters from your accountant verifying that your business is healthy and legally registered.
Next, the lender will ask for your bank statements from the last two months. They are looking to see exactly how much cash you have sitting in your checking and savings accounts.
They want to verify that you actually have enough liquid money to cover the down payment and the closing costs. They will also scrutinize your statements for large, unexplained deposits.
If your parents suddenly transferred ten thousand dollars into your account as a gift, you will need to prove where that money came from. The bank will require a formal "gift letter" stating that the money is not a secret loan you have to pay back. By gathering all these documents early, you show the lender that you are organized, serious, and ready to do business.
Quick Fact Check: The 50% "Sourcing" Rule
Did you know underwriters track sudden deposits? If you make $4,000 a month and randomly deposit $2,100 in cash, the bank will pause your application until you prove where it came from.
My advice: Print your last 60 days of bank statements right now. Highlight any single deposit over $1,000 that is not your regular paycheck. Get the receipts or gift letters for those specific highlights today so you are not scrambling later.
Mastering the Debt-To-Income (DTI) Formula
If you are still scratching your head over how banks calculate your monthly debts, watch this quick breakdown before moving on. It completely changed how I look at my budget, and the tips in the rest of this guide will make a lot more sense once you see the math in action!
Youtube video
Now we arrive at the most misunderstood math problem in the entire real estate universe. Your Debt-to-Income ratio, or DTI, is essentially the master key that unlocks your loan approval.
Even if you make a massive salary and have a perfect credit score, a bad DTI can ruin your chances instantly. Simply put, DTI is the percentage of your gross monthly income that goes toward paying your monthly debts.
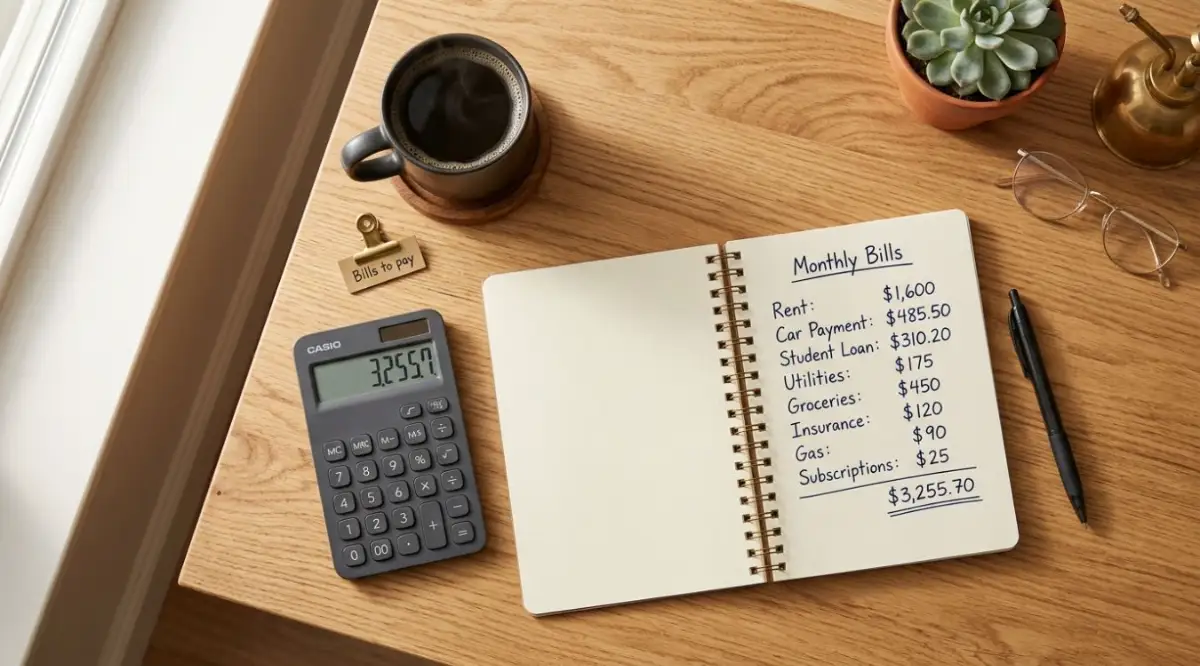
Let us break this down with a very simple, real-life scenario so it makes perfect sense. Imagine you make five thousand dollars every single month before any taxes are taken out of your paycheck. Now, add up all your fixed monthly debt payments.
This includes your car payment, your minimum credit card payments, and your student loan bills. Let us say all those debts combined cost you one thousand dollars every month.
To find your current DTI without the new mortgage, you divide your debt (1,000) by your income (5,000). That gives you a nice, healthy DTI of twenty percent. But here is the catch: lenders have to factor in your future estimated mortgage payment as well.
They add the new house payment, property taxes, and home insurance to your existing monthly debts. Most traditional lenders want to see that your total future DTI stays below a certain threshold, usually around forty-three percent.
A Quick DTI Comparison Table
I made the silly mistake of buying a brand-new car on finance just months before applying for my home loan, thinking my income was high enough to cover both. That one single car payment spiked my debt-to-income ratio so high that my lender almost laughed me out of the room. Learn from my panic attack and aggressively pay off your small debts instead of taking on new ones before you even think about applying.
If your DTI is sitting in the danger zone, you have two primary ways to fix the problem. You can either figure out a way to increase your monthly income, or you can aggressively pay down your existing debts.
Most people find it much easier to pay off a small credit card balance to eliminate that monthly payment entirely. Even removing a small fifty-dollar monthly payment can positively shift your DTI and give you more breathing room.
The Art of Shopping for the Perfect Lender
One of the biggest mistakes a new buyer can make is walking into their current bank and accepting the very first offer they get. You would never buy the first car you test drive without checking the price at another dealership.
The exact same logic applies to finding a financial partner for your property purchase. Different institutions have entirely different rules, interest rates, and fee structures for their customers.
You have a few different options when it comes to choosing where you get your money. Big national banks offer brand recognition and a sense of security, but they often have very strict approval rules.
Local credit unions, on the other hand, are deeply tied to the community and might offer lower fees. They tend to be more forgiving if your financial history has a few small bumps or bruises.
You also have the option of working with an independent mortgage broker. A broker does not lend you their own money; instead, they shop your application around to dozens of different banks.
This can save you a tremendous amount of time because they do all the heavy lifting and comparing for you. However, you should always ask a broker exactly how they get paid before you sign any agreements with them.
When you start contacting these professionals, you want to ask for a "Good Faith Estimate" or a "Loan Estimate" document. This standardized form breaks down the exact interest rate they are offering and all the hidden fees associated with the deal.
By collecting three or four of these estimates from different companies, you can easily compare them side-by-side. You will often be shocked to see that one company might charge thousands of dollars more in processing fees than a competitor.
Do not be afraid to negotiate with these loan officers. If Company A offers you a great interest rate but high fees, show that document to Company B. Often, they will lower their own fees just to win your business and get your signature on the dotted line.
Knowing the Difference: Prequalification vs Pre-Approval
As you start talking to lenders, you will hear two words that sound identical but mean completely different things. A "prequalification" is basically a casual, friendly chat with a bank about your finances.
You tell them how much you make and how much debt you have, but they do not actively verify anything you say. Based on your word alone, they give you a rough guess of how much house you can afford.
A prequalification letter is nice to have for your own personal budgeting, but it holds almost no real power. Real estate agents and home sellers know that this letter is just an unverified estimate. If you try to make a serious offer on a house with only a prequalification, you will likely be ignored.
A "pre-approval," on the other hand, is a serious, legally binding review of your financial life. This is when the bank actually pulls your official credit report and carefully reviews your tax returns.
An underwriter looks at your file and says, "Yes, we have verified this person's background, and we officially promise to lend them this specific amount of money." When you hand a pre-approval letter to a seller, it proves that you are a qualified, ready-to-act buyer.
Getting fully pre-approved requires more work upfront, but it gives you a massive advantage in a competitive market. It allows you to confidently make an offer the exact moment you find a home that you love.
The "Do Not Touch" Rules During the Waiting Game
Once you submit all your documents and the bank begins their official review process, you enter a very delicate phase. Your financial profile is basically frozen in time, and any sudden changes can instantly destroy your loan application.
You would be amazed at how many smart people accidentally ruin their own approval by making a silly mistake during this waiting period. Lenders will pull your credit one final time just days before you officially close on the house.
Rule number one is completely non-negotiable: absolutely do not open any new credit cards or take out any new loans. I have seen buyers get excited about their new house and immediately go finance ten thousand dollars worth of new living room furniture.
The moment that new furniture loan hits their credit report, their debt-to-income ratio spikes. The bank sees this new debt, panics, and pulls the plug on the mortgage completely.
Rule number two is just as important: do not quit your job or change careers during this process. Even if you are offered a new job with a significantly higher salary, the timing is terrible for a mortgage underwriter.
They like stability above all else, and a sudden career change makes them nervous about your probation period at the new company. If you absolutely must change jobs, you have to communicate this to your loan officer immediate