
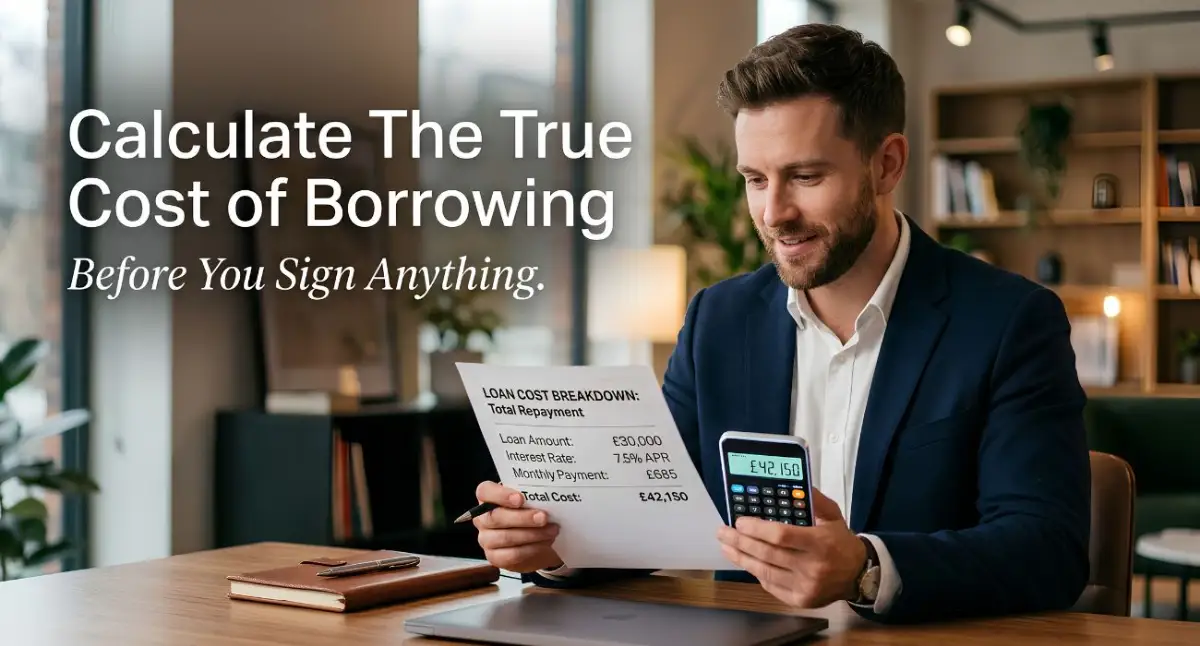
The Hidden Trap Behind "Easy Monthly Payments"
You sit across from a friendly loan officer, and they write down a monthly payment that fits your budget perfectly. It sounds like a great deal, right? That is exactly how they get you. Lenders know that if they keep your monthly bill looking small and harmless, you will probably ignore the thousands of dollars in hidden fees stacking up behind the scenes. I want to show you the real math behind borrowing money, so you can stop paying for your bank manager's summer vacations.
I still remember sitting at my kitchen table, staring blankly at a thick stack of loan papers. My hands were actually shaking a little bit as I held the pen, completely unsure if I was making a smart move or ruining my financial future. I thought I knew exactly how much money I was borrowing, but the numbers just did not add up in my head. The bank representative happily told me my "easy monthly payment," but I had this sinking feeling that I was missing something huge. I ended up signing the document that day out of pure exhaustion, and it became one of the biggest money mistakes I ever made. That single, rushed signature ended up costing me thousands of extra dollars I never planned for.
They know that if the monthly payment looks small enough, you might ignore the massive mountain of interest piling up in the background. This creates a terrible cycle where you pay your bill every single month, but your actual debt barely goes down. It feels like you are running on a treadmill that keeps speeding up, leaving you exhausted and financially drained.
This hidden trap destroys mental peace for countless families. You wake up in the middle of the night wondering why your bank balance is always so low, even though you are working harder than ever. The anxiety of never-ending debt starts to cast a dark shadow over your everyday life.
I want to help you understand exactly how to look past the fancy marketing talk and uncover the actual numbers. By changing how you view these agreements, you can protect your hard-earned money and your peace of mind. We are going to look closely at the real math behind borrowing, entirely for your educational benefit.
The Short Version (Key Takeaways):
- The advertised "interest rate" is bait; always demand to know the exact APR.
- Low monthly payments usually mean your timeline is stretched out, costing you thousands more in back-end interest.
- Never sign without looking at an "Amortization Schedule" so you can track where every dollar goes.
- Walk away immediately if the lender tries to charge you a fee for paying off your balance early.
Cracking the Code: How to Expose the Actual Price of Borrowing Money
Before you even think about putting your signature on a legal financial document, you need to become your own financial detective. The numbers printed in bold letters at the top of the page rarely tell the whole story. To protect yourself, you have to look deeply at the tiny text hidden at the bottom of those agreements.
Let me break this down into clear, everyday concepts that you can easily use right now. We are going to strip away the confusing bank jargon and look at the raw truth of how loans actually work. Once you understand these mechanics, nobody will ever be able to trick you with a "low monthly payment" again.
Stop Looking at the Interest Rate and Start Looking at the APR
This is where the biggest misunderstandings happen for most people looking to borrow money. The lender will often advertise a very attractive, low Interest Rate to catch your attention. You might see a big banner promising something like "Only 5% Interest!" and think you found an amazing deal.
However, the advertised interest rate is just the cost of borrowing the base money, also known as the principal. It completely ignores all the extra fees, charges, and administrative costs the lender forces you to pay. This is why you must always look for the Annual Percentage Rate (APR) instead.
The APR gives you a much more honest picture of what you will actually pay over a full year. It bundles the base interest rate together with all the hidden setup fees into one clear percentage. If a lender offers a 5% interest rate but the APR is 8%, that means they are hiding a lot of extra costs in the fine print.
Pro Tip: I learned the hard way that ignoring the APR is like buying a cheap car and forgetting you have to pay for expensive repairs later. Whenever I review any financial offer now, I immediately ask, "What is the exact APR?" and if they hesitate to tell me, I walk away.
Three Questions Your Loan Officer Hopes You Won't Ask:
- What exactly is the APR, including all your setup and origination fees? (This forces them to reveal the true markup).
- Is there a prepayment penalty if I clear this debt next year? (This stops them from trapping you).
- Can I see the full amortization schedule before I sign? (This shows you exactly how much of your cash goes to interest vs. principal in the first 12 months).
Uncovering the "Hidden Factory" of Loan Fees
Lenders often act like they are doing you a massive favor by giving you money, but borrowing is just a business transaction. They make their profit through a confusing web of extra charges that most people never notice until it is too late. You need to know exactly what to look for on that paperwork.
First, check for an Origination Fee. This is a sneaky charge the lender demands just for doing the paperwork to process your loan. Sometimes it is a flat fee, but often it is a percentage of the total amount you are borrowing. If you borrow $10,000 and they charge a 5% origination fee, they take $500 right off the top, leaving you with less money than you asked for.
Then, there is the extremely dangerous Prepayment Penalty. Let us say you get a bonus at work and want to pay your debt off early to save on interest. Some agreements actually charge you a heavy fine for paying them back too fast! They do this because your early payment ruins their plan to collect years of interest from you.
Always ask the representative directly: "Will I be penalized if I pay this balance off ahead of schedule?" If the answer is yes, that agreement is designed to keep you trapped in debt for as long as possible. A fair agreement should always allow you to clear your balance early without punishing you for being responsible.
The Truth About the Repayment Timeline
Time is the secret weapon lenders use to squeeze more money out of your pocket. Stretching a loan over a long period makes the monthly payments look incredibly small and easy to manage. This is exactly how they convince you to sign for more money than you actually need.
Let us look at a practical scenario to make this clear. Imagine you are taking out a $20,000 auto loan at a 6% interest rate. The salesperson asks if you want to pay it back over three years or seven years.
If you pick the seven-year option, your monthly payment will drop significantly, which feels great at first glance. But because you are borrowing the money for four extra years, the bank gets to charge you interest every single month for that entire extra time. By the time you finally finish paying, you will have paid thousands of dollars more overall compared to the three-year option.
Myth vs Reality: The "Affordable" Payment Trap
There are so many common myths floating around about how borrowing works. Let us clear up some of the most dangerous ones right now so you can make highly educated decisions.
The Myth: If I can easily afford the monthly payment, it means I can safely afford the loan.
The Reality: A low monthly payment often just means the loan is stretched out over a very long time. You might end up paying double the original amount in interest alone over the long run.
The Myth: The bank would not offer me this money if they did not think I could afford it.
The Reality: The bank is looking out for their profit, not your financial safety. They calculate the maximum amount you can possibly pay before going completely broke, which leaves you with zero room for emergencies.
The Myth: Refinancing to lower my monthly payment is always a smart financial move.
The Reality: Refinancing often restarts your repayment clock back to zero. You might get a lower payment today, but you will pay significantly more in interest over your lifetime.
The Simple Math You Can Do at Home
You absolutely do not need to be a math genius or hire an accountant to figure out the real numbers. You just need a basic calculator and a clear head before you sit down to sign. I am going to show you a simple method to find the true cost of any financial agreement.
First, take your exact monthly payment amount and multiply it by the total number of months you will be paying. For example, if you pay $300 a month for 60 months, you multiply 300 by 60. The result is $18,000.
Now, look at the original amount of money you actually received in your hand from the lender. Let us say you only borrowed $14,000 to begin with. Subtract the $14,000 from the $18,000 you calculated in the first step.
That remaining $4,000 is the True Cost of Borrowing. That is the actual price you are paying just for the privilege of using someone else's money. When you look at the total cost as a raw dollar amount instead of a percentage, it suddenly becomes very easy to decide if the deal is actually worth it.
Let's Look at a Real Math Breakdown:
Imagine you are financing a $20,000 car at a 6% rate.
- Option A (3-Year Loan): You pay $608 a month. Total interest paid by the end = $1,900.
- Option B (7-Year Loan): You pay just $292 a month. Total interest paid by the end = $4,545.
Notice how Option B drops your monthly bill by more than half, but secretly steals over $2,600 extra from your pocket in the long run? That is the hidden trap working against you.
The first time I did this simple math for my own auto loan, I honestly felt sick to my stomach realizing I was paying thousands of extra dollars just for the privilege of borrowing. My biggest advice is to never let the bank do the math for you; pull out your phone and spend two minutes running these numbers yourself before you even pick up a pen.
Comparing the Advertised Deal vs The True Reality
To make this completely clear, let us look at a simple comparison. When you understand the difference between what they sell you and what you actually pay, you gain massive control over your money.
This table shows exactly why you can never trust the large, bold print on a flyer or an email offer. The real details that affect your bank account are always buried deep in the pages you are expected to skip over.
Why the Concept of "Amortization" Matters to You
The word "amortization" sounds like a complicated term only bankers use, but it is actually a very simple concept that you need to grasp. It simply refers to the schedule of how your debt gets paid down over time. Understanding this schedule is the key to seeing why early payments feel so frustrating.
When you first start making payments, you might assume your money is split evenly between the principal amount and the interest fee. Sadly, that is rarely how agreements are structured in the real world. Lenders heavily front-load the interest charges at the very beginning of your timeline.
For the first few years, almost your entire monthly payment goes straight toward paying off the bank's interest fee. Only a tiny fraction of your money actually goes toward reducing the original amount you borrowed. This is exactly why you can pay $500 a month for two years, only to realize your main debt has barely moved an inch.
By asking the lender for a full amortization schedule before you sign, you can see exactly where every single dollar is going. You can clearly see how much pain you will go through in the early years. If the schedule looks heavily biased toward interest, you might want to reconsider taking the deal altogether.
If you are still a bit confused about how banks front-load your payments, watch this quick video to see exactly how amortization secretly eats up your cash. Seeing the math on a screen will make the rest of the money-saving tips in this guide so much easier to use!
Real-Life Scenario: The "Emergency Repair" Trap
Let us imagine a very common situation that forces people into bad agreements. Your home roof starts leaking badly during a storm, and you need $10,000 immediately to fix it before water destroys your house. You are stressed, panicking, and just want the problem solved as fast as possible.
A local lender offers you a quick approval loan to cover the repairs. They tell you the payment is just $250 a month, which easily fits your budget right now. Because you are in a rush to save your house, you quickly sign the digital document without reading the terms.
A year later, you check your balance and realize you still owe $9,500. You are confused because you have already paid them $3,000 over the past year! This is the exact moment you realize the true cost of borrowing in a state of panic.
If you had taken just thirty minutes to calculate the math before signing, you would have seen the heavy origination fees and the 20% interest rate buried in the text. Panic and urgency are a lender's best friends. Always force yourself to slow down, even in an emergency, to do the basic math we discussed above.
The Power of Being Prepared
Educating yourself about these financial mechanics gives you an incredible advantage. You no longer have to sit quietly while a representative rushes you to sign at the bottom of the page. You now have the exact knowledge needed to ask hard questions and demand clear answers.
When you ask a lender about their APR, their prepayment penalties, and their amortization schedule, their attitude will change instantly. They will immediately realize they are dealing with an educated individual, not someone they can easily take advantage of. Knowledge is the ultimate shield against bad financial agreements.
I want you to take these concepts and use them as your personal checklist the next time you need funding. Never let anyone make you feel bad for taking your time to read every single line of a contract. Your signature is incredibly powerful, and you should never give it away until you know the exact price tag attached to it.
Next-Level Strategies to Outsmart Tricky Lenders
Now that you know how lenders hide the real math, it is time to flip the script entirely. You can actually use a few advanced strategies to take complete control of the negotiation process. Lenders a